Quick answer: If you’re asking why is my credit score zero, the short version is that it isn’t. FICO and VantageScore scores run from 300 to 850, so a 0, a dash or “N/A” means no score could be calculated, usually because your credit file is too new, too thin or hasn’t been updated recently. It’s fixable, and most people can get a first score within about six months.
Key takeaways
- There’s no such thing as a 0 credit score. A blank or zero means “unscorable,” not “terrible.”
- A FICO Score generally needs at least one account that’s been open six months and at least one account reported to a bureau in the last six months.
- VantageScore 4.0 can score some files with just one to five months of history, so you may see a VantageScore before a FICO Score.
- Having no score is different from having a low score. Lenders treat them differently, and the fix is different too.
Why is my credit score zero when scores start at 300?
As of November 2026, the base FICO Score range is 300 to 850, and recent VantageScore models (3.0, 4.0 and later) use the same range. Nothing in either system produces a zero. So when an app, a bank dashboard or a loan denial letter shows 0, it’s almost always a placeholder for “we couldn’t generate a score.”
That’s an important distinction. A 520 tells a lender you’ve had trouble repaying. A blank tells them they have nothing to go on. Some lenders will still work with a no-score applicant, especially for secured cards and starter products. Few will approve a big unsecured loan.
The most common reasons you have no credit score
Scoring models need enough recent data to work with. You’ll usually come up blank for one of these reasons:
- You have no credit file at all. If no lender has ever reported an account in your name, the bureaus have nothing to score. The CFPB calls these consumers “credit invisible.”
- Your file is too new. You opened your first card or loan a few weeks ago. FICO needs at least one account that’s been open for six months.
- Your file has gone dormant. You paid off your last loan or closed your last card years ago, and nothing has been reported in the past six months. The history is still there, but it’s stale.
- Your only accounts don’t report. Rent, phone and utility bills usually don’t show up on credit reports unless you add them yourself.
- The app couldn’t match your file. A recent move, a name change, a typo in your Social Security number or a credit freeze can stop an app from pulling your report, and some apps show that as 0 or N/A.
- There’s a serious error on your report. A report that wrongly lists you as deceased, or mixes your file with someone else’s, can stop scoring entirely.
The CFPB’s updated estimate, published in June 2025, found that about 2.7% of U.S. adults were credit invisible in 2020, roughly half its earlier figure. Many more people do have a file but can’t be scored because it’s too thin or too old.
No credit score vs. a thin file vs. bad credit
| Situation | What it means | What a lender sees | The fix |
|---|---|---|---|
| Credit invisible | No file at any bureau | No report, no score | Open a first account that reports |
| Unscorable thin file | A file exists but it’s too new or too old to score | A report, but no score | Add a reporting account and wait for it to age |
| Bad credit | A scorable file with late payments, collections or high balances | A low score | Repair: pay on time, lower balances, dispute errors |
If you’re in the third row, our guide to why your credit score dropped is a better starting point. This article is for the first two.
Why your app shows 0 but a lender sees a score (or the other way around)
It’s common to see a VantageScore in a free app and get told by a lender that you have no FICO Score. That isn’t a glitch. The two models have different minimums.
VantageScore’s own documentation says version 4.0 can score consumers with one to five months of history on their file, and files that haven’t been updated in six months but have older activity. FICO’s conventional models are stricter. Experian lists the requirements for a first FICO Score as at least one account active for at least six months, plus at least one account reported in the last six months.
Each bureau also holds its own file. If your only account reports to Equifax, an app that pulls TransUnion may show nothing. Our explainer on the three credit reporting agencies covers why your files can differ.
How to check what’s actually on your credit report
Before you try to build anything, find out which situation you’re in. It’s the quickest way to answer why is my credit score zero for your own file. Pull your free reports from all three bureaus at AnnualCreditReport.com, the site authorized under federal law. Then check:
- Is there a file at all? If a bureau says it can’t find you, you’re credit invisible with that bureau.
- How old is your oldest open account? Under six months means you’re probably just waiting.
- When was the last update? Nothing reported in six months means the file has gone stale.
- Is everything accurate? Wrong name, wrong accounts or a deceased flag need a dispute with that bureau right away.
The fastest legitimate ways to get your first score
You can’t buy a score, and anyone selling a “new credit file” is selling fraud. What works is getting at least one account reported and letting time pass. These are the usual first steps:
- Become an authorized user on a parent’s or partner’s card that has a long, clean history. Many issuers report authorized users to the bureaus, though it helps most if the primary cardholder pays on time and keeps balances low.
- Open a secured credit card. You put down a deposit that becomes your limit. Use it for one small bill a month and pay it in full. See our picks for a credit builder card.
- Take out a credit-builder loan. The lender holds the money in savings while you make payments, then releases it. Every payment is reported.
- Get rent and bills reported. Rent-reporting services and Experian Boost can add on-time rent, phone, utility and streaming payments. Experian notes that Boost works once you already meet the minimum FICO requirements, so it’s a booster, not a starting point.
If you’d rather not use a credit card at all, we cover other options in how to build credit without a credit card.
Habits that keep your score stuck at zero
Some people stay unscorable for years without realizing why. These are the usual culprits:
- Using only a debit card. Debit card spending comes out of your bank account, so it’s never reported as credit, no matter how responsible you are.
- Opening a card and never using it. An account with no activity can stop being updated, and some issuers close inactive cards. A small recurring charge, paid off each month, keeps it alive.
- Closing your only account. Once your last open account is paid off or closed and nothing new reports for six months, FICO can’t score you anymore.
- Applying everywhere at once. Several applications in a short window add hard inquiries and denials without adding history.
If you’ve been wondering why is my credit score zero even though you pay every bill on time, the first habit is often the answer. On-time payments only count when they’re reported.
How long it takes to go from no score to a real one
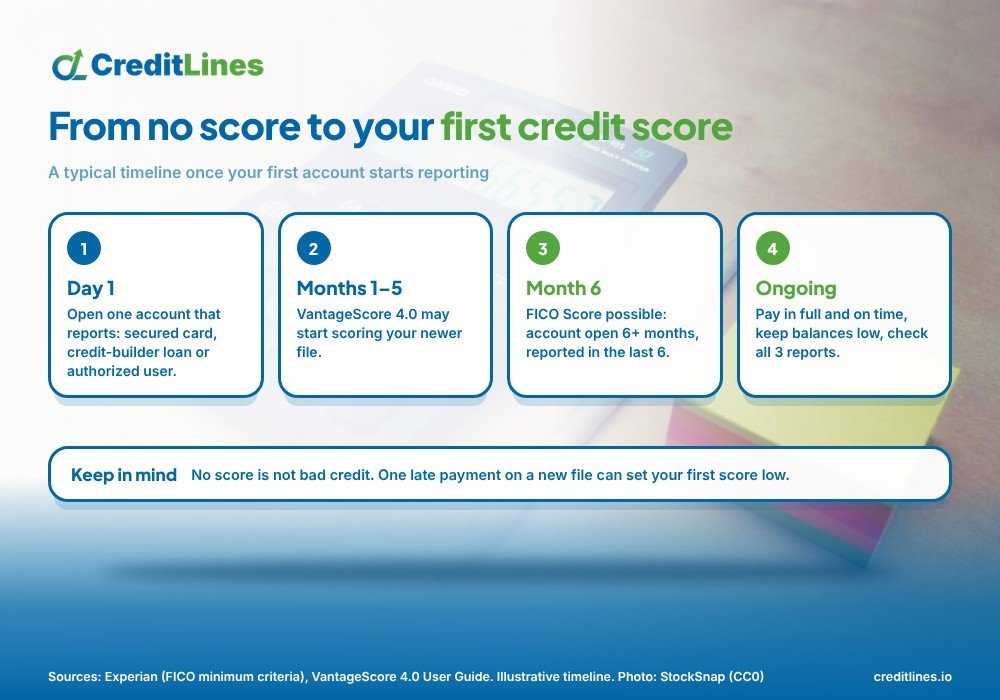
For most people the clock starts when the first account reports. A VantageScore may appear within the first month or two. A FICO Score usually follows once that account has been open about six months and has a recent update.
What you do in those six months matters more than how fast you get there. One late payment on a brand-new file can set your first score well below where it would otherwise land. Keep the balance small, pay in full and on time, and don’t open several accounts at once just to speed things up.
Who shouldn’t rush any of this: anyone who can’t comfortably pay a new monthly bill. A credit card you can’t pay off does more harm than having no score at all.
Frequently asked questions
Can your credit score be 0?
No. Base FICO Scores range from 300 to 850, and recent VantageScore models use the same range. A zero shown in an app or on a lender’s screen is a placeholder that means no score could be calculated, usually because the credit file is missing, too new or hasn’t been updated in the past six months.
Is having no credit score worse than having bad credit?
Not necessarily. No score means lenders have no history to judge, while bad credit shows a record of missed or late payments. Many starter products, such as secured cards and credit-builder loans, are designed for people with no score. A low score can be harder to fix because the negative marks stay on your report for years.
Will checking my own credit report hurt my score?
No. Checking your own credit reports or scores is a soft inquiry and never affects your score. Hard inquiries only happen when a lender pulls your credit because you applied for new credit. You can check your reports from all three bureaus for free as often as AnnualCreditReport.com allows without any impact.
Does paying rent build a credit score?
Only if it’s reported to a credit bureau. Most landlords don’t report on-time rent automatically. You can ask whether your landlord or property manager uses a rent-reporting service, sign up for one yourself, or link qualifying online rent payments through Experian Boost once you meet the minimum requirements for a FICO Score.
Why do I have a credit score with one bureau but not another?
Each bureau keeps its own file, and lenders don’t always report to all three. If your only account reports to one bureau, the other two may have too little information to score. Check all three reports and, when you open new accounts, ask the lender which bureaus it reports to.
Sources
- myFICO, What is a FICO Score? (score range)
- Experian, What Are the Credit Score Ranges? (November 4, 2026)
- Experian, Experian Boost (FICO minimum criteria and eligible bills)
- VantageScore 4.0 User Guide (minimum scoring criteria)
- CFPB, Technical correction and update to the CFPB’s credit invisibles estimate (June 2025)
- AnnualCreditReport.com, free credit reports
This article is for educational purposes only and is not financial advice. Scoring rules and products change, so confirm details with the lender or credit bureau.