Quick answer: As of November 2026, the best-paying CDs pay about 4.60% APY for a 1-year term and up to about 5.00% APY for longer terms, mostly from online banks. That is far above the FDIC national average of 1.76% for a 1-year CD. CD rates have edged up since the Federal Reserve raised its benchmark rate in September 2026, so locking in part of your savings now while keeping some flexible can be a smart move. The best-paying CD for you, though, is not just the highest APY, it is the top rate on a term that matches when you will need your money.
A certificate of deposit is one of the few places you can still earn a guaranteed return above 4% with zero risk to your principal. After a long stretch of rate cuts, the Federal Reserve raised rates again in September 2026, and top CD yields have edged up with it. This guide shows you the current best-paying CD rates, where to find them, how to choose the right one, and how to squeeze the most out of your savings.
What is a CD and how does it pay?
A certificate of deposit, or CD, is a savings account that pays a fixed interest rate for a set period of time, called the term. In exchange for locking your money away, you typically earn a higher rate than a regular savings account, and the rate is guaranteed for the entire term no matter what happens in the market.
A few essentials to know:
- APY is what matters. The annual percentage yield reflects your true yearly earnings including compound interest, so compare CDs by APY, not the plain interest rate.
- Your money is insured. CDs at FDIC-insured banks and NCUA-insured credit unions are protected up to $250,000 per depositor, per institution.
- There is a catch: early withdrawal penalties. Pull your money out before the term ends and you usually forfeit some interest, often 90 to 180 days’ worth or more.
You’ll often see the term “high-yield CD.” It isn’t a special type of account. It’s a regular CD that pays well above the national average, usually offered by online banks and credit unions with lower overhead than big branch banks. As of November 2026, top high-yield CDs pay around 4.5% APY or more, compared with an FDIC national average of 1.76% for a 1-year CD.
Current best CD rates in 2026
As of November 2026, the highest CD rates we verified are about 4.60% APY for a 1-year term and about 4.80% to 5.00% APY for terms of 18 months to 5 years. That’s far above the FDIC national average of 1.76% for a 12-month CD and 1.41% for a 60-month CD.
The table below shows top rates by term, with examples taken directly from each bank’s own website. Rates change often, sometimes weekly, so confirm the APY, minimum deposit and early withdrawal penalty before you open an account.
| Term | Top APY we verified | Example institutions (minimum deposit) |
|---|---|---|
| 6 months | 4.05%–4.35% | Popular Direct 4.35% ($10,000); Bread Savings 4.05% ($1,500) |
| 1 year | 4.45%–4.60% | Popular Direct 4.60% ($10,000); Bread Savings 4.45% ($1,500) |
| 18 months | 4.80%–4.85% | Bread Savings 4.85% ($1,500); Popular Direct 4.80% ($10,000) |
| 2 years | 4.55%–4.80% | Popular Direct 4.80% ($10,000); Bread Savings 4.55% ($1,500) |
| 3 years | 4.60%–4.85% | Popular Direct 4.85% ($10,000); Bread Savings 4.60% ($1,500) |
| 5 years | 4.70%–5.00% | Popular Direct 5.00% ($10,000); Bread Savings 4.70% ($1,500) |
As of: Popular Direct APYs effective October 26, 2026, and Bread Savings APYs as of November 1, 2026, both from the banks’ own websites.
For contrast: the FDIC’s national average rate, published October 19, 2026, was 1.76% for a 12-month CD and 1.41% for a 60-month CD. A top online CD can pay more than twice the national average, which is why shopping around matters.
Why CD rates turned higher in late 2026, and what that means now
CD rates track the Federal Reserve’s benchmark rate. After cutting rates three times in late 2025, the Fed held steady for most of 2026, then raised its target range by 0.25 percentage point to 3.75%–4.00% on September 16, 2026, saying inflation remained elevated.
On October 28, 2026, the Fed held rates at that level, but two of the 12 voting members wanted another increase. The next decision is due December 9, 2026.
For savers, that has meant better CD offers. Top 1-year rates in our August 2026 table topped out around 4.50%. They now reach about 4.60%. If the Fed raises rates again, CD yields could keep rising, so a CD ladder lets you lock in today’s rates on part of your money while keeping some cash free to reinvest later.
Where to find the best-paying CDs
The best rates are rarely at big national banks, which often pay little on deposits. Look instead to:
- Online banks. With low overhead and no branches, they consistently offer some of the highest CD rates.
- Credit unions. Member-owned and not-for-profit, they frequently top the rate tables, though you may need to meet membership criteria, which is often easy.
- CD marketplaces. Platforms that let you open CDs from many banks in one place, often with very low minimums, make it easy to compare and spread your money across institutions.
Comparing several of these is the surest way to find the best-paying CD for your term.
Types of CDs
Not all CDs are the same, and the type affects both your rate and your flexibility.
| CD type | How it works | Trade-off |
|---|---|---|
| Traditional CD | Fixed rate for a fixed term, penalty for early withdrawal | Best rates, least flexibility |
| No-penalty CD | Lets you withdraw early without a penalty | Usually a slightly lower rate |
| Jumbo CD | Higher rate for large deposits, often $75,000 or more | Requires a big balance |
| Bump-up CD | Lets you raise your rate once if rates rise | Often a lower starting rate |
| Brokered CD | Bought through a brokerage, can be sold before maturity | More complex, with price risk if sold early |
For most savers chasing the best rate, a traditional CD wins on yield. If you want flexibility in case you need the money or rates climb, a no-penalty or bump-up CD trades a little yield for options.
How to choose the best-paying CD for you
The highest APY on the page is not automatically your best choice. Match the CD to your situation:
- Match the term to your timeline. Only lock away money you will not need until the CD matures. If you might need it in six months, do not choose a two-year CD, however good the rate.
- Weigh the early withdrawal penalty. Check how many days’ interest you would forfeit if you had to break the CD early.
- Consider a no-penalty CD for emergency-adjacent money, so you keep access.
- Do not chase a tiny rate difference into the wrong term. An extra 0.05% is not worth locking up money you may need.
The CD ladder: a smarter way to lock in rates
If you cannot decide on one term, a CD ladder solves the dilemma by spreading your money across several CDs with staggered maturity dates.
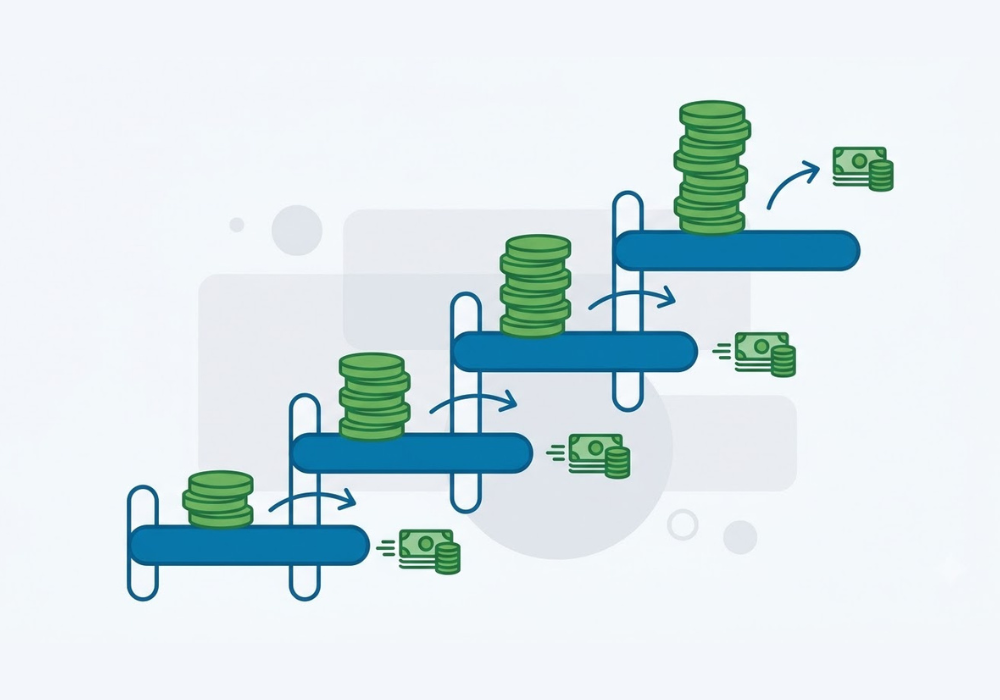
Here is how it works. Instead of putting $10,000 into a single CD, you split it into five CDs of $2,000 each, with terms of one, two, three, four, and five years. Every year, one CD matures, giving you access to cash. You can then spend it or reinvest it into a new five-year CD. Over time, you hold a mix of CDs, earning higher long-term rates while still having money coming available each year. A ladder gives you the best of both worlds: strong rates and regular liquidity, plus protection against locking everything in right before rates change.
Watch out for early withdrawal penalties
The biggest risk with a CD is not losing money, since your principal is insured, it is needing your money early. Traditional CDs charge a penalty for early withdrawal, commonly ranging from about 90 days’ interest on shorter terms to 180 days or more on longer ones. A stiff penalty can wipe out much of your earned interest. That is why matching the term to your timeline matters so much, and why a no-penalty CD can be worth a slightly lower rate for money you might need.
CD vs. high-yield savings account
Both are safe, insured places to earn interest, but they serve different needs.
- A CD locks in a fixed rate for a set term. It is best for money you will not touch, and it shines when rates are falling because your rate is protected.
- A high-yield savings account pays a variable rate and lets you withdraw anytime. It is best for emergency funds and money you may need, but its rate drops when the market falls.
Many savers use both: a high-yield savings account for accessible cash, and CDs to lock in today’s rates on money they can commit for longer.
How to open a CD
- Compare rates and terms across online banks, credit unions, and CD marketplaces, focusing on APY, term, minimum deposit, and the early withdrawal penalty.
- Choose a term that matches your timeline, so you will not need the money before maturity.
- Open the account online, which usually takes minutes.
- Fund the CD with the required minimum deposit.
- Note your maturity date and auto-renewal terms, since many CDs automatically renew, sometimes at a lower rate, if you do nothing.
Tips to maximize your CD earnings
- Lock in sooner rather than later if rates are falling, to secure today’s yield.
- Build a ladder to balance higher rates with regular access to cash.
- Avoid breaking a CD early to sidestep penalties.
- Track your maturity date so you can decide whether to renew, move, or withdraw rather than auto-renewing into a lower rate.
- Use a no-penalty CD for money you want to earn on but might need.
Frequently asked questions
What is the best-paying CD right now?
As of November 2026, the highest CD rates we verified are about 4.60% APY for a 1-year CD and up to 5.00% APY for a 5-year CD, from online banks such as Popular Direct and Bread Savings. Minimum deposits range from $1,500 to $10,000, and rates change often, so confirm on the bank’s site.
Are CD rates going up or down in 2026?
CD rates have been rising since late summer 2026. The Federal Reserve raised its benchmark rate to 3.75%–4.00% on September 16, 2026, citing elevated inflation, and held it there on October 28. Top 1-year CD rates have climbed from about 4.50% in August to about 4.60% as of November 2026.
Where can I find the highest CD rates?
Online banks and credit unions typically offer the highest CD rates, since they have lower costs than big national banks. CD marketplaces also let you compare and open CDs from many banks in one place, often with low minimum deposits.
Should I lock in a CD now or wait?
It depends on when you need the money and where rates go next. As of November 2026 the Fed has been raising rates, so CD yields could rise further. Locking in part of your savings now secures today’s rate, while a shorter term or a CD ladder lets you reinvest if rates keep climbing. If rates fall instead, a longer CD protects your yield.
What is a CD ladder?
A CD ladder spreads your money across several CDs with staggered maturity dates, so one matures each year. It lets you earn higher long-term rates while keeping regular access to a portion of your cash and reduces the risk of locking everything in at the wrong time.
Are CDs safe?
Yes. CDs at FDIC-insured banks and NCUA-insured credit unions are protected up to $250,000 per depositor, per institution. Your principal is not at market risk, though early withdrawal penalties can reduce your earned interest if you take money out before maturity.
What is the difference between a CD and a high-yield savings account?
A CD locks in a fixed rate for a set term and penalizes early withdrawal, making it ideal for money you will not need soon. A high-yield savings account pays a variable rate and allows withdrawals anytime, making it better for emergency funds and flexible cash.
What is a high-yield CD?
A high-yield CD is a standard certificate of deposit that pays a rate well above the national average. They are usually offered by online banks and credit unions. As of November 2026, top high-yield CDs pay around 4.5% APY or more, versus a 1.76% FDIC national average for 1-year CDs. They’re still FDIC- or NCUA-insured up to $250,000.
How much does a $10,000 CD earn in a year?
At 4.60% APY, about the top 1-year rate as of November 2026, a $10,000 CD earns roughly $460 in interest over 12 months. At the FDIC national average of 1.76%, the same deposit earns about $176. Interest is usually taxable as ordinary income in the year you earn it.
This article is for educational purposes only and is not financial advice. CD rates change frequently and vary by institution, term, and region, and any rates here reflect November 2026 and will change. Verify current APYs, minimums, and penalties directly with the bank or credit union before opening an account.