
Quick answer: Capital One car loans are offered through Auto Navigator, an online tool that lets you pre-qualify with a soft credit check, which does not affect your credit score, to see real personalized rates and monthly payments before you set foot in a dealership. You then use that pre-qualification to buy a car from one of more than 15,000 participating dealers. Capital One accepts a wide range of credit, roughly down to a 500 credit score, requires at least $1,500 a month in income, and has a low $4,000 minimum loan. The main catches are that it only works at participating dealers, it is not available in Alaska or Hawaii, and the pre-qualified rate is not guaranteed until you finalize at the dealer. It is best for buyers who want to shop financing risk-free.
Most car buyers dread the financing part, partly because applying usually dings your credit. Capital One’s Auto Navigator is one of the few tools that lets you see your real car-loan rate without hurting your score, which is a genuine advantage. But there are important catches that every buyer should understand first. This honest review breaks down how a Capital One car loan works, the rates and requirements, the limitations, and who it is right for.
What is a Capital One car loan and Auto Navigator?
A Capital One car loan is auto financing from Capital One, one of the largest banks in the United States, offered primarily through its Auto Navigator platform. Auto Navigator is an online car-shopping and financing tool that lets you do two things in one place: browse actual vehicles available at participating dealerships, and pre-qualify for financing on those cars.
The idea is to bring the financing step forward, so you walk into the dealership already knowing roughly what you can borrow and at what rate, rather than negotiating financing blind. It combines car shopping and loan pre-qualification into a single, consumer-friendly experience.
How Auto Navigator’s pre-qualification works
This is Capital One’s standout feature. Auto Navigator lets you pre-qualify using a soft credit inquiry, which has no impact on your credit score, and in return you see a real, personalized estimated rate and monthly payment based on your actual credit profile.
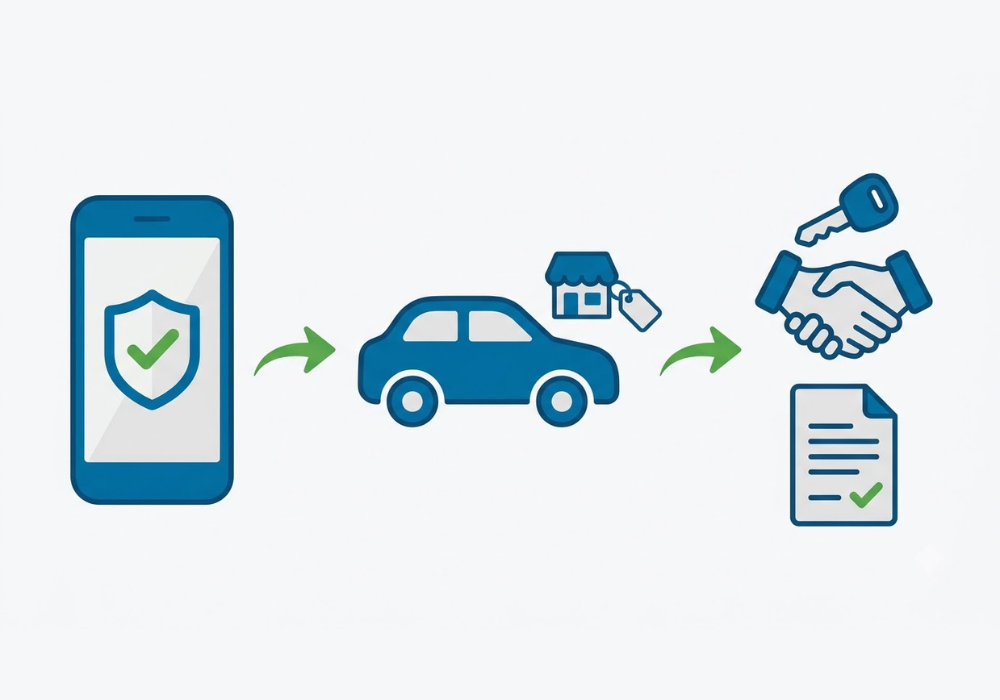
The process takes only a couple of minutes. You enter your personal details, income, and an estimated loan amount, and Capital One performs a soft pull to return a genuine rate range and payment estimate. From there, you browse inventory across a network of more than 15,000 dealerships, and for each car the tool shows the pre-qualified terms you would get. Because it is a soft pull, you can shop and compare as much as you like without any damage to your credit, which is exactly what makes it so useful for early-stage car shopping.
Pre-qualification is not a guarantee
Here is the most important caveat, and the one that trips up buyers. Your Auto Navigator pre-qualification is an estimate, not a locked-in contract. The final rate and terms are not confirmed until you complete the financing process at the dealer, which involves a hard credit check and verification of your information, and Capital One does not guarantee the dealer will offer the same terms you saw.
A few things protect your rate. Try to keep the vehicle’s price within about 10% of the loan amount you estimated, since straying far from it can change your terms. A pre-qualification is typically valid for 30 days. And be aware that some buyers have reported their pre-qualified rate not holding once at the dealership, so treat the estimate as a strong starting point and a negotiating benchmark, not a promise. Comparing it against other lenders’ pre-approvals is always smart.
Capital One car loan rates and terms
Capital One offers loan terms generally ranging from 36 to 72 months. The “as low as” rates the bank advertises are reserved for buyers with excellent credit and are updated monthly, so they are a floor, not what most people get.
Your actual rate depends on several factors, including your credit history, the total amount financed, your down payment, the loan term you choose, the loan-to-value ratio, and the vehicle itself. In practice, rates tend to be competitive for buyers with strong credit, roughly 660 and above, while the APR ceiling can be high for lower-credit borrowers. Because the only way to see your true number is to pre-qualify, and doing so does not affect your score, it is worth checking your personalized rate before assuming anything.
Capital One car loan eligibility requirements
Capital One accepts a broad range of applicants, but there are clear requirements to pre-qualify:
- Age: at least 18, or your state’s minimum.
- Income: at least $1,500 per month.
- Location: a valid street address in the contiguous United States, including APO or FPO addresses. Auto Navigator’s dealer network excludes Alaska and Hawaii.
- Credit: a wide range is accepted, reportedly down to around a 500 score, though better credit earns better rates.
- Existing Capital One accounts: you cannot have three or more open Capital One auto accounts or a total Capital One auto balance over $100,000, and existing accounts must be in good standing.
- Loan size: a minimum loan of $4,000, which is lower than the $7,500 minimum at some big banks.
- Identification: a Social Security number or tax ID.
Meeting these does not guarantee approval, but it makes you eligible to pre-qualify and see estimated terms.
Vehicle restrictions to know
Capital One financing comes with vehicle rules that can catch buyers off guard:
- Participating dealers only. You must buy from a dealership in the Auto Navigator network, so it does not cover private-party purchases or every dealer.
- Eligible vehicle types include cars, SUVs, minivans, and light trucks.
- Age and mileage limits apply to used vehicles.
- Excluded makes. Certain discontinued brands, including Daewoo, Isuzu, Oldsmobile, Saab, and Suzuki, are not eligible, and some other makes and models may be excluded too.
What about refinancing?
Capital One has offered auto loan refinancing at various points, but availability has changed over time, and recent sources indicate the focus is on purchase financing through Auto Navigator, with refinancing limited or unavailable. If refinancing an existing auto loan is your goal, confirm the current availability and terms directly with Capital One before counting on it, and compare dedicated refinance lenders.
Pros and cons of a Capital One car loan
The upside:
- True soft-pull pre-qualification that shows real personalized rates with no impact on your credit score.
- Shop cars and financing together across a large network of more than 15,000 dealers.
- Accessible to a wide credit range, including lower-credit borrowers who can at least see their options risk-free.
- A low $4,000 minimum loan, below many big banks.
- The backing of a major, established bank.
The trade-offs:
- Participating dealers only, so it does not work for private-party sales or every dealership.
- Not available in Alaska or Hawaii.
- The pre-qualified rate is not guaranteed and can change at the dealer.
- A high APR ceiling for lower-credit borrowers.
- Vehicle restrictions on age, mileage, and certain makes.
- Refinancing availability is uncertain and may be limited.
Who is a Capital One car loan best for?
A Capital One car loan is an excellent fit if you want to see your real financing rate before visiting a dealer without any hit to your credit, you plan to buy from a participating dealer, and you value shopping cars and financing in one place. It is especially useful for buyers with fair or rebuilding credit who want a free, risk-free look at what they would actually pay.
It is less ideal if you want to buy from a private seller or a non-participating dealer, if you live in Alaska or Hawaii, if you need a guaranteed locked rate rather than an estimate, or if your main goal is refinancing. In those cases, another lender may serve you better.
How to get a Capital One car loan
- Pre-qualify on Auto Navigator at Capital One’s site, entering your details and income for a soft-pull estimate that does not affect your score.
- Browse participating-dealer inventory and view the pre-qualified terms shown for each car.
- Choose a vehicle priced close to your estimated loan amount, ideally within about 10%.
- Take your pre-qualification to the dealer and finalize, which involves a hard credit check and verification.
- Review the final terms carefully and compare them against any other pre-approvals before signing.
Tips to keep your pre-qualified rate
- Stay within about 10% of your estimated loan amount when choosing a car.
- Finalize within 30 days, before the pre-qualification expires.
- Compare with other lenders’ pre-approvals so you can push back if the dealer’s final terms are worse than expected.
- Keep your credit stable between pre-qualifying and finalizing, avoiding new debt or missed payments.
Frequently asked questions
What is a Capital One car loan?
A Capital One car loan is auto financing offered through Auto Navigator, an online tool that lets you pre-qualify with a soft credit check and shop for cars at participating dealers. You see real personalized rates before visiting a dealership, then finalize the loan there.
Does Capital One Auto Navigator hurt your credit score?
No. Pre-qualifying through Auto Navigator uses a soft credit inquiry, which does not affect your credit score. Your score is only affected later if you move forward and the dealer runs a hard credit check to finalize the loan.
Is Capital One Auto Navigator pre-qualification guaranteed?
No. Pre-qualification is a conditional estimate based on your information and a soft credit review, not a guaranteed contract. Final terms are confirmed at the dealer after a hard credit check, and Capital One does not guarantee the dealer will offer the same terms.
What credit score do you need for a Capital One car loan?
Capital One accepts a wide range of credit, reportedly down to around a 500 score, and does not publish a strict minimum. Better credit earns better rates, with competitive rates generally going to scores around 660 and above and a higher APR ceiling for lower credit.
What are the requirements for a Capital One car loan?
You must be at least 18, earn at least $1,500 a month, and have a valid address in the contiguous U.S., so not Alaska or Hawaii. You also need a minimum $4,000 loan, cannot have three or more open Capital One auto accounts, and need a Social Security or tax ID number.
Can I use a Capital One car loan at any dealership?
No. You must purchase from a dealer in the Auto Navigator network of more than 15,000 participating dealerships. It does not cover private-party purchases or dealers outside the network, which is an important limitation to check before relying on it.
Does Capital One offer auto loan refinancing?
Capital One has offered refinancing at times, but availability has changed and recent information suggests the focus is on purchase financing, with refinancing limited or unavailable. Confirm current refinance availability directly with Capital One and compare dedicated refinance lenders.
This article is for educational and informational purposes only and is not financial or lending advice, and it is not affiliated with or endorsed by Capital One. Rates, terms, eligibility, vehicle rules, and product availability change over time, and pre-qualified terms are estimates that are not guaranteed. Verify current details directly with Capital One and compare multiple lenders before borrowing.

This Post Has One Comment